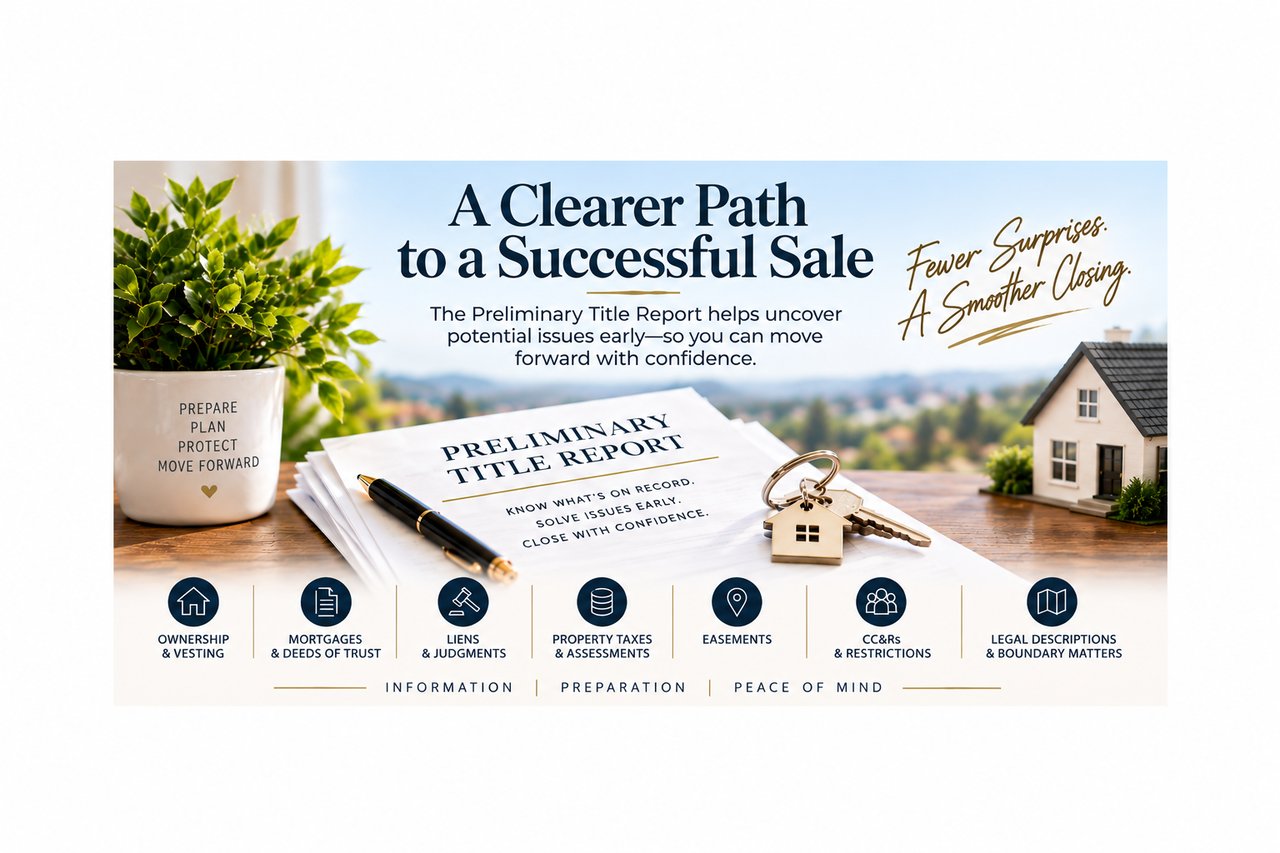
When selling a home in California, there is one document that can uncover potential problems before they become expensive closing delays: the Preliminary Title Report, commonly called the “Prelim.”
As a listing agent representing a seller, I believe it is important to make sure the preliminary title report is ordered early in the transaction and carefully reviewed. Depending on the transaction and brokerage procedures, the listing agent, transaction coordinator, escrow officer, or title company may initiate the order.
But what exactly is a preliminary title report, and why does it matter?
What Is a Preliminary Title Report?
A preliminary title report is prepared by a title insurance company before it issues a title insurance policy.
The report identifies how title to the property is currently held and lists recorded matters that may affect the property or the title insurer’s willingness to insure it.
Think of it as an early look at the property’s recorded title history and the issues that may need to be addressed before ownership can be transferred.
What Can a Preliminary Title Report Reveal?
A prelim may identify important matters such as:
• Current ownership and vesting — Is the property owned individually, jointly, through a trust, corporation, LLC, or another entity?
• Mortgages and deeds of trust — Existing loans generally need to be addressed as part of the closing.
• Liens and judgments — Certain liens or judgments may need to be paid, released, or otherwise resolved before the transaction can close.
• Property taxes and assessments — Delinquent taxes, special assessments, and other recorded obligations can affect the transaction.
• Easements — Another person, utility company, governmental entity, or neighboring property may have recorded rights affecting a portion of the property.
• CC&Rs and restrictions — Recorded covenants, conditions, restrictions, and other agreements may affect how the property can be used.
• Legal descriptions and boundary-related documents — These can become particularly important when there have been lot line adjustments, subdivisions, easements, or other changes involving the property.
Why Should a Seller Care?
Discovering a title problem a few days before closing can create unnecessary stress.
For example, imagine discovering shortly before closing that an old deed of trust was never properly reconveyed, a lien remains of record, the seller’s trust requires additional documentation, or a recorded easement affects the property in a way nobody anticipated.
Some title issues can take time to resolve.
Obtaining the preliminary title report early gives the seller, listing agent, escrow, and title company more time to identify and address potential problems before they interfere with closing.
Lot Line Adjustments Require Extra Attention
A preliminary title report becomes particularly important when a property has been affected by a Lot Line Adjustment (LLA) or other boundary modification.
In these situations, I would want more than just the preliminary title report.
I would also request copies of the relevant recorded documents referenced in the report, which may include:
• Recorded Lot Line Adjustment documents
• Updated legal descriptions
• Partial reconveyances
• Deeds of trust
• Easements
• Agreements affecting the adjusted property
• Other recorded documents affecting the applicable portion of the land
This is an important distinction: seeing an exception listed on a preliminary title report is not necessarily the same as reviewing the underlying recorded document.
When a transaction involves an unusual title or boundary issue, obtaining those documents can help the parties understand exactly what has been recorded.
Questions involving the legal effect of those documents should be directed to the title company and, when appropriate, a qualified real estate attorney.
A Preliminary Title Report Is Not a Guarantee of Clear Title
Another important point for sellers and buyers to understand is that a preliminary title report is not itself a title insurance policy or a guarantee that there are no title problems.
It is part of the title company's process leading toward issuance of a title insurance policy and identifies exceptions, requirements, and recorded matters relevant to the proposed coverage.
That is why simply receiving the prelim is not enough.
It should be reviewed.
The Bottom Line
A smooth real estate transaction is often the result of identifying potential problems before they become emergencies.
For sellers, getting the preliminary title report early can help uncover liens, ownership issues, easements, restrictions, boundary matters, and other recorded issues while there is still time to address them.
For listing agents, making sure the prelim is ordered and reviewed is an important part of staying ahead of potential closing problems—even when someone else in the transaction physically places the order.
Selling a home? Preparation before the property reaches the closing table can make all the difference.
Tina Lucarelli (310) 738-8089
Luxury Real Estate Advisor
Westlake Village | Thousand Oaks | Conejo Valley | Greater Los Angeles
This article is provided for general real estate information and is not legal or title advice. Questions concerning the legal effect of title documents should be directed to a qualified title professional or real estate attorney.